William Perraudin
| William Perraudin | |
|---|---|
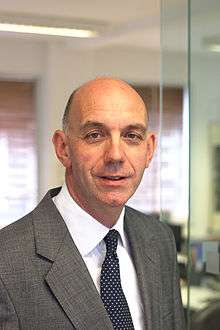 William Perraudin | |
| Website | http://www.riskcontrollimited.com/ |
| M. Ishaq Nadiri | |
|---|---|
| Doctoral advisor | Dale W. Jorgenson[1] |
William R. M. Perraudin is a British economist. He is an Adjunct Professor and former Chair of Finance at Imperial College London,[2] specialising in the fields of risk and pricing of debt instruments. He is a Director of the risk management software and consultancy firm Risk Control Limited.[3]
As an expert in the field of risk as applied to financial regulation, Perraudin has been a special advisor to the Bank of England.[4] He has long taken the position that the financial models in use by major institutions are insufficiently conservative.[5]
Education
From 1977 to 1981 William Perraudin studied French and History at the University of Oxford. From 1981 to 1983 he studied for a MSc in Economics at London School of Economics, before gaining a PhD in Economics from Harvard University.[6] He earned an M.S. in Applied Mathematics - 1987 to 1988 - also from Harvard.
Career
Before moving to Imperial,[7] Professor Perraudin headed the finance group of Birkbeck College, University of London.[8] He also taught at Cambridge University
He is an associate editor of Quantitative Finance, the Journal of Banking and Finance and the Journal of Credit Risk.
Selected Publications
- Capital Floors, the Revised SA and the Cost of Loans in Switzerland, 2015.[9]
- Default Probability Risk and Securitisation Capital, 2015.[10]
- Comment on Antoniades and Tarashev, 2015.[11]
- (with Georges Duponcheele and Alexandre Linden)How to Revive the European Securitisation Market: a Proposal for a European SSFA, 2014.[12]
- (with Georges Duponcheele and Daniel Totouom-Tangho) Calibration of the Simplified Supervisory Formula Approach, 2014.[13]
- Securitisation Purchases by the ECB - What is ‘Senior Enough’?, 2014.[14]
- Covered Bond versus ABS Liquidity: A Comment on the EBA’s Proposed HQLA Definition, 2014.[15]
- High Quality Securitisation: An Empirical Analysis of the PCS Definition, 2014.[16]
- Quantitative Impacts of BCBS 269 Securitisation Capital Approaches, 2014.[17]
- Structured Credit Products: Pricing, Rating, Risk Management and Basel II, 2004. ISBN 1-904339-26-3, ISBN 978-1-904339-26-7.[18]
- After the Apocalypse: Lessons from the Global Financial Crisis, Demos.[19]
- (with Robert Lamb) Dynamic Default Rates.[20]
- (with Paolo Vitale) Interdealer Trade and Information Flows in a Decentralized Foreign Exchange Market.[2]
References
- ↑ Ph.D. Thesis Advisees(Accessed September 2016)
- 1 2 "NBER Publications by William Perraudin". NBER. Retrieved 2010-04-17.
- ↑ http://www.riskcontrollimited.com
- ↑ "Quarterly Bulletins (Financial Stability)". Bank of England. 2001-01-16. Retrieved 2010-04-17.
- ↑ "The Reliability of Credit Risk Models". CEPR. Retrieved 2010-04-17.
- ↑ "About the Speakers". ICMA Centre. Retrieved 2010-04-17.
- ↑ http://www3.imperial.ac.uk/people/w.perraudin
- ↑ http://www.moodys.com/cust/content/Content.ashx?source=staticcontent/Free%20Pages/CreditRiskConference/Conf07/conf07files/MAARC_Formation_Announcement.pdf
- ↑ Capital Floors, the Revised SA and the Cost of Loans in Switzerland
- ↑ http://www.riskcontrollimited.com/insights/default-probability-risk-and-securitisation-capital/
- ↑ http://www.riskcontrollimited.com/insights/comment-on-antoniades-and-tarashev/
- ↑ http://www.riskcontrollimited.com/insights/how-to-revive-the-european-securitisation-market-a-proposal-for-a-european-ssfa/
- ↑ http://www.riskcontrollimited.com/insights/calibration-of-the-simplified-supervisory-formula-approach/
- ↑ http://www.riskcontrollimited.com/insights/securitisation-purchases-by-the-ecb-what-is-senior-enough/
- ↑ http://www.afme.eu/WorkArea/DownloadAsset.aspx?id=10360
- ↑ http://www.riskcontrollimited.com/insights/high-quality-securitisation-an-empirical-analysis-of-the-pcs-definition/
- ↑ http://www.riskcontrollimited.com/insights/quantitative-impacts-of-bcbs-269-securitisation-capital-approaches/
- ↑ "Wilmott: Serving The Quantitative Finance Community". Global Investor. Retrieved 2010-04-17.
- ↑ "Apocalypse" (PDF). Imperial College. Retrieved 2010-04-17.
- ↑ http://www3.imperial.ac.uk/pls/portallive/docs/1/48761701.PDF
External links
- BBC interview
- http://uk.linkedin.com/pub/william-perraudin/7/3b4/777
- Risk Management Laboratory, Imperial College
- http://www.cepr.org/Pubs/new-dps/dplist.asp?dpno=753
- Academic homepage at Imperial
- http://www.cepr.org/Pubs/new-dps/dplist.asp?dpno=753
- http://en.scientificcommons.org/43940082
- Risk Control Ltd
- Works by or about William Perraudin in libraries (WorldCat catalog)